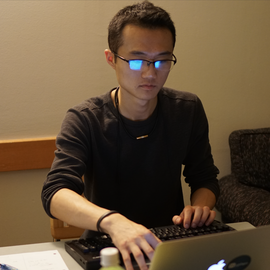
Sailun(Celsius) Xu
Quantitative Researcher at Citadel Securities
Biography
Sailun works as a quantitative researcher at Citadel Securities. He focuses on the strategy and monetization for FICC(Fixed Income Commodities and Currencies)
He got a Bachelor of Arts in Mathematics and Computer Science from Cornell Unversity and a Master in Machine Learning from Carnegie Mellon University.
email: intial 38 at cornell.edu
Interests
- Statistical Inference
- Optimization
- Reinforcement Learning
- Application of Machine Learning to Finance and Recommender System
Education
-
Master in Machine Learning, 2019
Carnegie Mellon University
-
B.A. in Mathematics(Cum Laude), Computer Science, 2018
Cornell University
Recent Publications
(2020).
ChemBO: Bayesian Optimization of Small Organic Molecules with Synthesizable Recommendations.
Proceedings of the Twenty Third International Conference on Artificial Intelligence and Statistics.
(2020).
Video Content Swapping Using GAN.
Arxiv.
Academia Experience
Graduate Researcher
Carnegie Mellon University
- Advisor: Jeff Schneider
- We implemented a Bayesian Optimization framework using a Gaussian Process that allows efficient sampling and exploration of synthesizable molecules that maximizes any given score
- We proposed a new kernel for molecules based on the Optimal Transport(OT) that has shown better overall performance than the baseline: finger print kernels, which only serializes a molecule and ignores the structure

Undergraduate Researcher
Cornell University
- Advisor: Kilian Q. Weinberger
- Netflix challenge using the factorization machine model
- Profiled the training time bottleneck function and fully vectorized the part using einsum, reducing the run time per call from 700ms to 150ms
- Reached a RMSE at 0.92, beating the 0.98 baseline using support vector machine
Industry Experience
Quantitative Researcher
- FICC(Fixed Income, Currencies and Commodities) Strategy & Monetization Research
- PTA(post-trading analysis) of our live trade
- Analyzed and fine-tuned our delay model for historical sim using the live trigger-to-trade latency and impact time at the exchange
- Quant Dev: Implemented our trading strategy; designed and implemented multiple tools to easily manipulate and visualize the data